First-time buyer scams and red flags in Ireland in 2026, how to protect your deposit
By David S · 30 October 2026
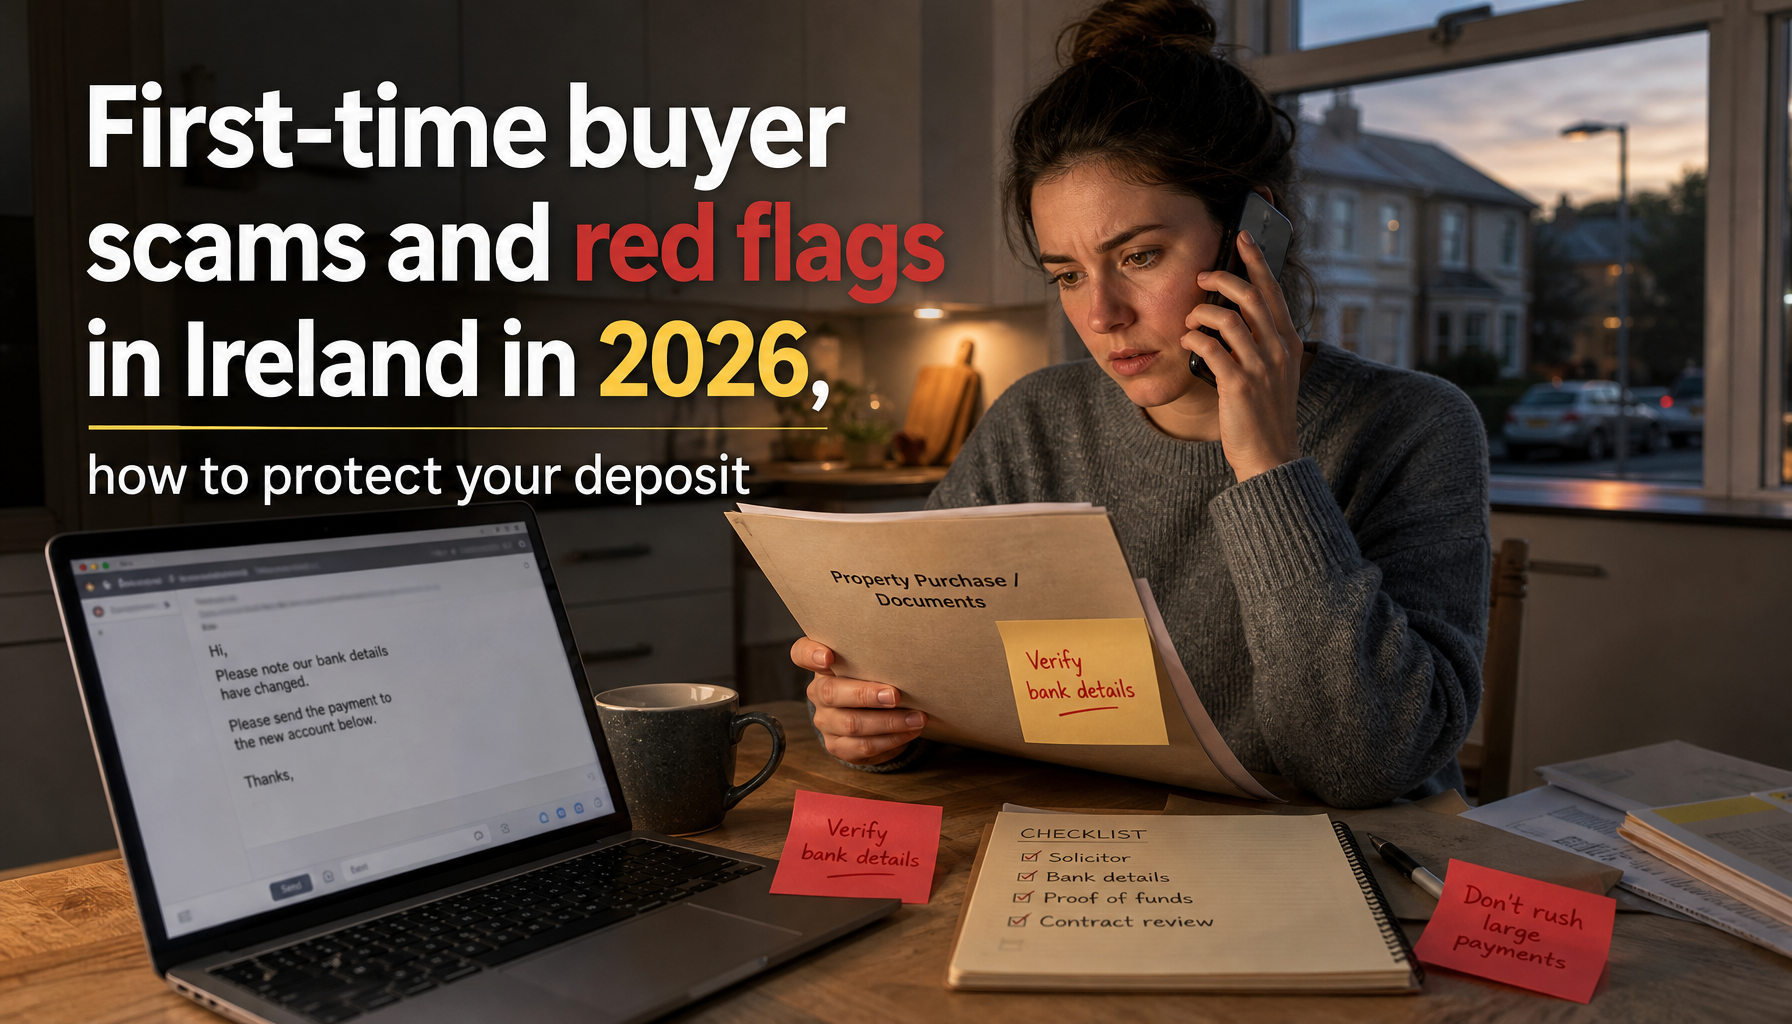
For many first-time buyers, saving the deposit is the biggest milestone before the keys ever come into view. In 2026, scammers are targeting that milestone with more timing-sensitive tactics, especially around payment changes and pressured “fast closing” requests. This is where first-time buyer scams Ireland can cause serious financial harm, most often through deposit fraud and confusion linked to property conveyancing.
This explainer sets out the most common red flags, why they happen, and the practical steps you can take to protect your money. It is not a substitute for professional advice, but it will help you ask better questions and notice the warning signs early.
Why deposit scams spike at the payment stage
When buying property, the process is a chain of handovers. You sign documents, agree terms, and then move money at specific points. Scammers thrive on moments where paperwork is moving quickly and buyers feel a deadline pressure.
In practice, deposit-related fraud usually hinges on one of three gaps:
- Payment details change, and the buyer is told to update bank details urgently.
- Identity and authority are unclear, for example, who exactly is requesting the funds and why.
- Conveyancing steps are rushed, reducing the chance the buyer verifies the instruction properly.
Even if the seller is genuine, scammers may impersonate parties in the chain. They might use email, phone calls, or messaging to create urgency and to move money before checks can be completed.
Top red flags for first-time buyer scams Ireland in 2026
Below are warning signs that frequently appear in deposit fraud scenarios. Any one item should be enough to pause. A combination of items is a strong signal to escalate checks.
1) “Bank details have changed” close to the deposit deadline
This is one of the most common scam patterns. You receive a message saying the account details provided earlier are no longer valid, and you are asked to transfer the deposit to a different bank account immediately.
Red flag cues:
- The message arrives after you have already agreed on deposit payment details.
- The request uses urgency language, such as “final chance” or “payment needed today”.
- The message does not come through the same channel you have used for official communications.
What to do: Do not treat the new details as automatic. Ask your solicitor, and only follow updated payment instructions after they are confirmed through proper professional channels.
2) Pressure to pay before conveyancing is properly underway
Buying involves checks and documentation. If someone suggests paying a deposit in a way that sidesteps your solicitor’s involvement, be cautious.
Red flag cues:
- You are told to send money before contracts are in place.
- You are discouraged from asking questions or contacting your solicitor directly.
- The seller or intermediary cannot clearly explain how and when the payment will be reflected in the legal process.
Delays can be frustrating, but meaningful legal steps protect you. If you feel rushed, that is a major warning sign.
3) Mismatched identity, inconsistent contact details
Scammers often struggle to maintain consistent details across communication channels. Look for discrepancies.
Red flag cues:
- Email addresses differ slightly from earlier communications.
- Phone numbers or email domains change suddenly without explanation.
- Names or roles are vague, for example, “representative” without clear authority.
Identity verification is not about mistrusting everyone. It is about confirming you are paying the correct party for the correct transaction.
4) “New buyer offer, deposit required now” messages
Sometimes scammers target buyers who are actively searching. They may claim the buyer is selected for a property and that a deposit is needed immediately to secure it.
Red flag cues:
- You never saw the property through normal listings or verified viewings.
- The person cannot provide a straightforward paper trail for the sale.
- The instructions focus more on speed of payment than on legitimate steps.
If you are using RightPlace.ie to browse, you can start by keeping your search within transparent, verifiable listings and then moving to solicitor-led verification before any major payment.
5) Unclear or missing documentation about the deposit
You should understand what the deposit is for, when it is due, and how it will be handled in the legal process.
Red flag cues:
- No clear written agreement on deposit amount or timing.
- Payment instructions are provided without context.
- You cannot reconcile deposit payment details with contract documentation provided by your solicitor.
If the explanation feels incomplete, it probably is. Ask for the document trail.
How to protect your deposit, practical checklist for 2026
When it comes to deposit safety, the best approach is to build a simple verification routine. The aim is to make it hard for a scam to take hold, even if someone tries.
Step 1: Keep your communications in a single professional channel
Try to ensure that all deposit payment instructions flow from your solicitor or via the confirmed contact method used in your conveyancing process. If a message appears in a different channel, treat it as unverified until confirmed.
Step 2: Verify payment details using a “known safe” method
Do not use the contact details included in a suspicious email or message. Instead, use the solicitor’s contact details you already have, for example from initial correspondence, and confirm the bank details verbally or through a secure method.
This is especially important if you receive a “changed bank details” request. A scammer may try to intercept and replace details right when you are most focused on closing the deal.
Step 3: Confirm the authority behind the request
If someone requests payment on behalf of a seller or an agent, ask for clarity on who they represent and how the request ties into the legal process. Your solicitor can usually help you interpret what is standard and what is not.
Step 4: Use a pause rule on urgent messages
Adopt a personal rule: if a payment message is urgent, you pause and verify. Scammers depend on you reacting instantly. A short delay for confirmation is a protective action, not a loss.
Step 5: Keep evidence of what you were told and when
Save emails, messages, and screenshots of instructions. If anything looks inconsistent later, having a record helps your solicitor act quickly. Even if the transaction is legitimate, clear records reduce confusion.
Property conveyancing red flags beyond scams
Deposit fraud is only one risk. Problems in property conveyancing can also create delays and stress. While you should not assume wrongdoing, you should watch for operational confusion that can be exploited.
Common issues include:
- Missing or unclear documentation about the transaction steps.
- Multiple parties emailing instructions without a clear single “source of truth”.
- Inconsistent references to the property address, title details, or sale parties.
If you spot these issues, speak to your solicitor early. A well-managed conveyancing process creates fewer opportunities for incorrect or fraudulent instructions to go unnoticed.
Where to find reliable guidance while you buy
Guidance sources can help you understand the process and the role of legal steps. For general housing and buyer information, consider the official and consumer-focused resources available from Citizens Information.
You can also use RightPlace.ie guides to plan your search, shortlist locations, and understand what matters between viewing and moving in. For example, these reads can help you structure your thinking in 2026:
- What estate agents do between offer and closing in 2026 (and why it matters)
- New homes in 2026: timelines that actually matter, site handover, snagging, and move-in
- Property market signals in 2026: how to spot a price reset in your local area
What to do if you suspect deposit fraud
If you think you have fallen for a scam or received suspicious payment instructions, act quickly. Don’t wait for someone else to fix it.
- Contact your solicitor immediately and explain what happened, including the timing and the payment instructions received.
- Stop further payments until the situation is clarified.
- Gather evidence, including screenshots, email headers where possible, and any transaction references.
Even if it turns out to be a misunderstanding, the sooner you verify, the better your chances of preventing further harm.
Choosing a safer path for your next viewing and offer
Ultimately, protecting your deposit is about reducing uncertainty. When you keep the process structured, you make it harder for scams to create momentum.
Here are three practical ways to strengthen your position when searching for a home in 2026:
- Start with clear listings and a consistent route to viewings. If you are browsing, use reputable sources and compare multiple options, such as Homes for sale on RightPlace.
- Plan your next step before you need money. Have your solicitor details ready and confirm what information they will need if payment instructions change.
- Keep your communication safe and verifiable. Treat urgent payment changes as suspicious until confirmed by your solicitor.
Bottom line, deposit safety is process safety
First-time buyer scams Ireland are not just about criminals contacting you, they are about exploiting the stress and speed that often surrounds property purchase. In 2026, the red flags tend to cluster around deposit timing, payment instructions, and clarity of authority in property conveyancing.
If you remember one principle, make it this: never treat new payment instructions as confirmed just because they arrive urgently. Verify through your solicitor using known safe contact details, and pause when something does not feel right.
With a careful routine, you can focus on the real goal, finding the right home with confidence that your deposit is going where it should.